Building portfolio resilience amid higher rates
What you need to know
- Earnings outshine higher-rate headwinds. Strong corporate profits have helped stocks climb, despite the impact of higher interest rates, though bonds remain stuck in neutral as the monetary policy debate continues.
- Earning strength extends beyond AI. AI investment remains a powerful growth driver, but earnings strength has extended across a variety of sectors and regions, providing a more durable foundation beneath stock market gains.
- Higher rates may create opportunities. While elevated rates may test market sentiment in the near term, they may also offer advantages for goal-focused investors looking to build portfolio resilience with intention and discipline.
- Stay diversified, but favour equities. Canadian small- and mid-cap stocks, U.S. large-cap stocks, and emerging-market stocks appear particularly attractive in today's environment, in our view.
Portfolio tip
Rather than predict exactly where rates may move next or make a concentrated bet on any single market scenario, build portfolio resilience through diversification and goal alignment.
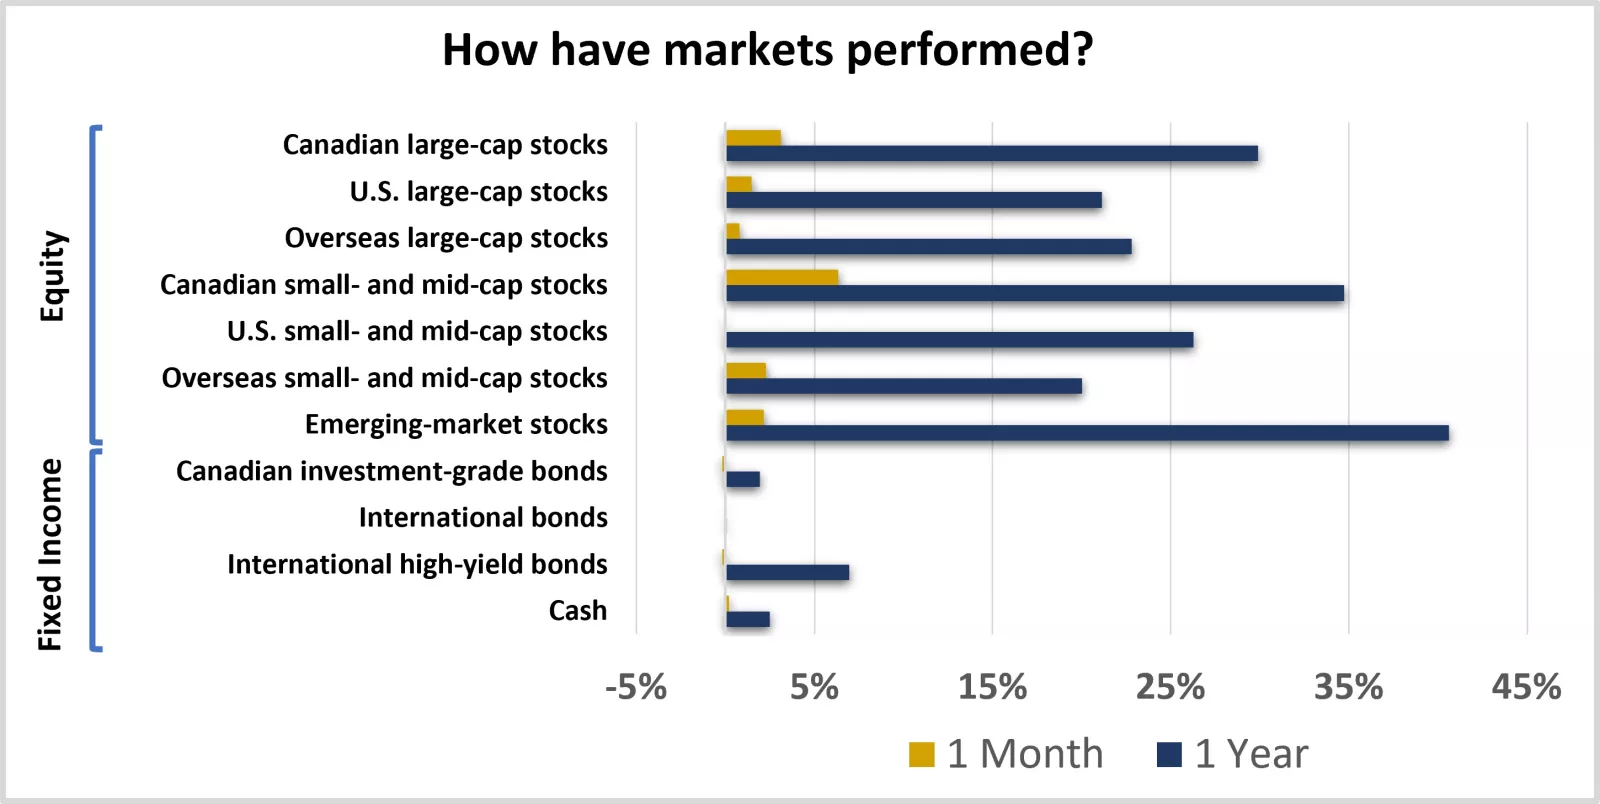
This chart shows the performance of equity and fixed-income markets over the previous month and year.
This chart shows the performance of equity and fixed-income markets over the previous month and year.
Where have we been?
Stocks climb as earnings outshine the impact of higher interest rates. Artificial intelligence, trade relations, geopolitics and central bank policy have all shared center stage this year, pulling markets in different directions at various times. Interest rates moved higher over the past couple of months amid renewed concerns about energy prices and persistent inflation against a backdrop of steady economic growth. As a result, the 10-year Government of Canada bond yield trended toward 3.75% while the 10-year Treasury yield recently climbed above 4.8%, toward levels not seen since 2023.
While higher rates have created a headwind for stock valuations, solid corporate profits have helped offset that pressure on returns. According to FactSet, full-year TSX earnings growth is now expected to exceed 25%, up 8% from the start of the year. Estimates for S&P 500 are for earnings growth to reach 31%, more than double the level anticipated at the beginning of the year.
AI investment remains a powerful growth driver, but it has not been the sole force behind recent market gains. Overall, the latest earnings season helped dampen concerns about the sustainability of AI-related spending and the returns it may generate. The U.S. large-cap technology sector is now expected to deliver 55% earnings growth in 2026, helping it regain traction in August. More broadly, renewed AI enthusiasm supported tech-oriented markets globally, helping to lift tech-heavy emerging-market equity toward the top of the performance rankings over the latest month.
Notably, solid corporate profit trends extend beyond technology. Commodity prices, including oil and precious metals, rallied in August, providing a tailwind for Canada's materials and energy sectors and helping Canadian equities take the lead.
Additionally, nearly every sector in the TSX and S&P 500 is expected to deliver positive earnings growth for calendar year 2026. Earnings expectations have also been revised higher across other major regions, including the eurozone, Japan, and the United Kingdom, helping to drive gains in overseas markets. This broad-based earnings momentum highlights the foundation of global economic growth that continues to support equity markets.
Bonds remain stuck in neutral as the monetary policy debate continues. While some recent consumer inflation data and market-based inflation expectations have shown encouraging signs, geopolitical uncertainty and trade negotiations remain key risks.
Some central banks have emphasized that more progress is needed to bring inflation down further, hinting at the potential for rake hikes. The Bank of Canada left its policy rate unchanged in early September, though noted their commitment to price stability.
Although bond investors continue to benefit from interest income, rising rates have limited total returns. As a result, bond returns have been relatively flat this year, particularly compared with strong gains in equities.
What do we recommend going forward?
Higher yields have strengthened the case for bonds as a strategic component of a diversified portfolio. With steady economic growth and persistent inflation pressures, we expect interest rates to remain elevated through the remainder of the year, with the 10-year Government of Canada bond yield likely fluctuating between 3.5% and 4.0% and the 10-year Treasury yield between 4.5% and 5.0%.
Though, rather than trying to predict exactly where rates may move next, bond investors should focus on three ways to position fixed-income allocations in today's environment:
- Use higher yields to your advantage. While bond price appreciation may be limited in the near term, higher yields improve the long-term return potential of fixed income. In our view, this strengthens the case for bonds as a strategic source of income and diversification within a well-diversified portfolio. This may be particularly relevant if you hold an overweight cash allocation that could be shifted toward higher-yielding fixed-income investments, especially if bonds have become too underweight in your portfolio.
- Emphasize diversification within bond allocations. With markets continuing to debate inflation and the direction of central bank policy, consider spreading bond allocations across Canadian and international bonds, while combining a range of maturities and credit qualities to enhance your portfolio's resilience and income potential. While diversification does not ensure a profit or protect against loss in a declining market, it can help manage risks associated with interest rate volatility and help keep your portfolio aligned with your investment objectives.
- Be intentional about tactical portfolio positioning. Although we continue to favour equities over bonds in the near term, given our expectation for continued economic resilience and broad-based earnings momentum, we do not believe investors should abandon fixed income. Instead, consider trimming exposure to investment-grade bonds, without straying too far from your goal-oriented strategic allocations, while retaining balanced allocations to international high-yield bonds. This positioning may help your portfolio benefit from income and growth opportunities amid a supportive economic backdrop.
Equities remain essential for preserving long-term purchasing power and, in our view, offer compelling near-term opportunities. Although higher interest rates may create headwinds for stock prices and geopolitical tensions, trade negotiations, election headlines, and policy uncertainty may fuel periodic volatility, we believe equities serve as a cornerstone of any strategy built to preserve long-term purchasing power. Moreover, maintaining diversified equity allocations represents a more disciplined approach to achieving long-term goals than making concentrated bets on a single market scenario.
We also believe several fundamental trends that underpin stock markets remain in place. Economic growth remains healthy, corporate earnings momentum is strong, labour markets are steady, and consumer spending appears supportive. While this backdrop may contribute to inflationary risks, it also helps the economy withstand higher interest rates and adapt to potential policy adjustments, potentially creating opportunities for disciplined investors.
Against this backdrop, we favour the following areas of the equity market, especially for investors considering an equity overweight relative to their strategic stock/bond mix:
- Canadian small- and mid-cap stocks, which we believe offer beneficial exposure to sectors linked to commodities and cyclical growth opportunities, such as materials, energy, and industrials.
- U.S. large-cap stocks, which we believe offer an attractive exposure to AI and relatively strong economic growth while helping to maintain a focus on quality. In the U.S., we favour the industrials and communications services sectors, which are well positioned to benefit from economic strength, infrastructure investment, and AI adoption, in our view.
- Emerging-market stocks, which we believe provides international exposure to global AI adoption beyond the U.S., and at relatively attractive valuations.
We’re here for you
While higher rates may test market sentiment in the near term, they may also offer advantages for goal-focused investors. Consider speaking with your financial advisor about how diversification, goal alignment, and opportunities created by higher yields and a constructive economic backdrop may help you enhance your portfolio's resilience.
If you don't have a financial advisor, we invite you to meet with an Edward Jones financial advisor to discuss whether your portfolio has been appropriately positioned to navigate the interest rate environment while supporting your financial goals and investment objectives.
Strategic portfolio guidance
Defining your strategic investment allocations helps to keep your portfolio aligned with your risk and return objectives, and we recommend taking a diversified approach. Our long-term strategic asset allocation guidance represents our view of balanced diversification for the fixed-income and equity portions of a well-diversified portfolio, based on our outlook for the economy and markets over the next 30 years. The exact weightings (neutral weights) to each asset class will depend on the broad allocation to equity and fixed-income investments that most closely aligns with your comfort with risk and financial goals.
Diversification does not ensure a profit or protect against loss in a declining market.
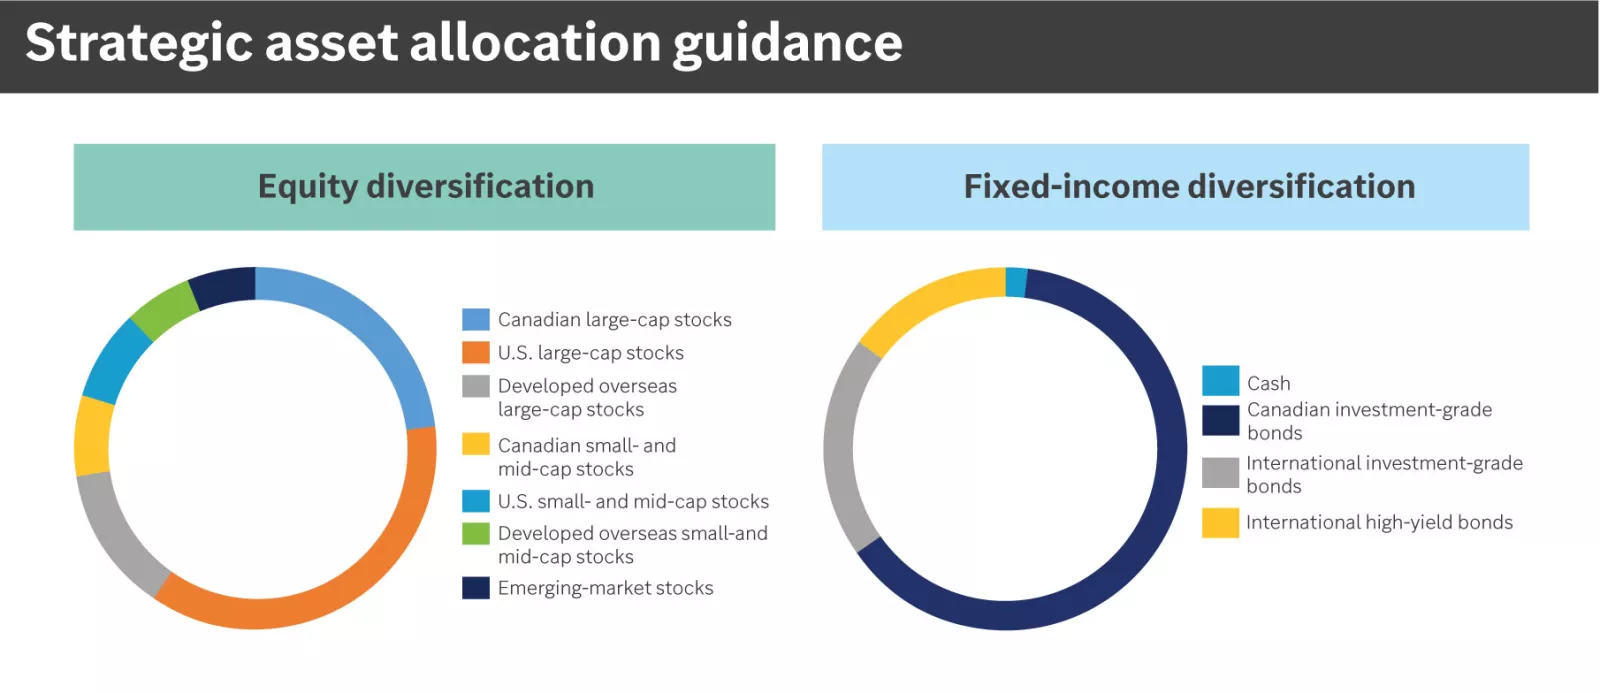
Within our strategic guidance, we recommend these asset classes:
Equity diversification: Canadian large-cap stocks, U.S. large-cap stocks, developed overseas large-cap stocks, Canadian small- and mid-cap stocks, U.S. small- and mid-cap stocks, developed overseas small- and mid-cap stocks, emerging-market stocks.
Fixed-income diversification: Canadian investment-grade bonds, international bonds, international high-yield bonds, cash.
Within our strategic guidance, we recommend these asset classes:
Equity diversification: Canadian large-cap stocks, U.S. large-cap stocks, developed overseas large-cap stocks, Canadian small- and mid-cap stocks, U.S. small- and mid-cap stocks, developed overseas small- and mid-cap stocks, emerging-market stocks.
Fixed-income diversification: Canadian investment-grade bonds, international bonds, international high-yield bonds, cash.
Opportunistic portfolio guidance
Our opportunistic portfolio guidance represents our timely investment advice based on current market conditions and a shorter-term outlook. We believe incorporating this guidance into a well-diversified portfolio may enhance your potential for greater returns without taking on unintentional risks, helping to keep your portfolio aligned with your risk and return objectives. We recommend first considering our opportunistic asset allocation guidance to capture opportunities across asset classes. We then recommend considering opportunistic equity sector and Canadian investment-grade bond guidance for more supplemental portfolio positioning, if appropriate.
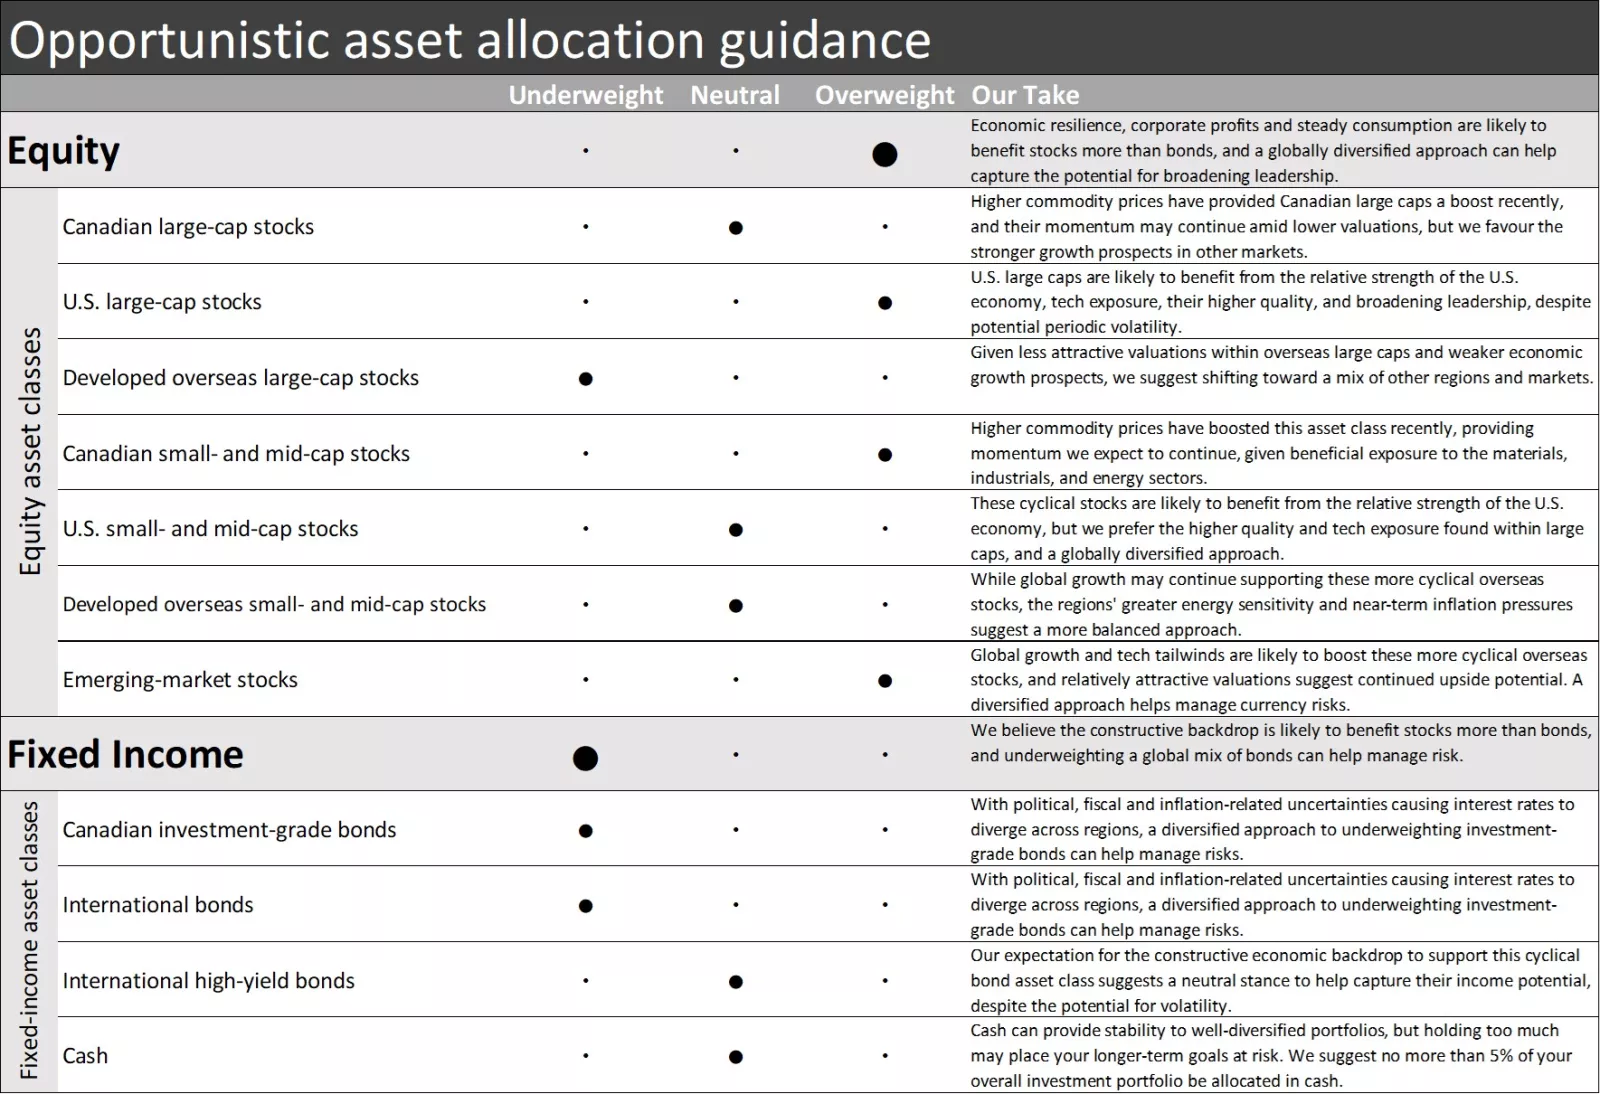
Our opportunistic asset allocation guidance is as follows:
Equity —overweight overall; underweight — Developed overseas large-cap stocks; neutral — Canadian large-cap stocks, U.S. small- and mid-cap stocks and developed overseas small- and mid-cap stocks; Overweight — U.S. large-cap stocks, Canadian small- and mid-cap stocks and emerging-market stocks.
Fixed income —underweight overall; underweight – Canadian investment-grade bonds and international bonds; neutral — international high-yield bonds and cash.
Our opportunistic asset allocation guidance is as follows:
Equity —overweight overall; underweight — Developed overseas large-cap stocks; neutral — Canadian large-cap stocks, U.S. small- and mid-cap stocks and developed overseas small- and mid-cap stocks; Overweight — U.S. large-cap stocks, Canadian small- and mid-cap stocks and emerging-market stocks.
Fixed income —underweight overall; underweight – Canadian investment-grade bonds and international bonds; neutral — international high-yield bonds and cash.
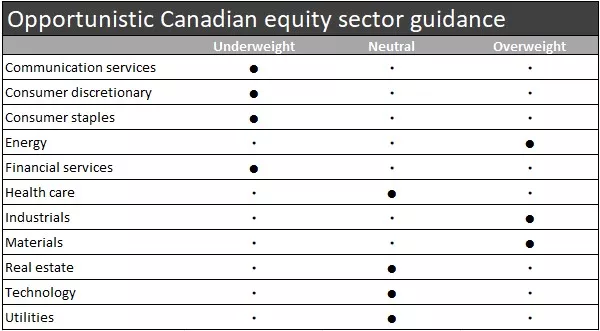
Our opportunistic Canadian equity sector guidance follows:
Overweight for energy, industrials, and materials
Neutral for technology, health care, real estate, and utilities
Underweight for communication services, consumer discretionary, consumer staples, and financial services and financial services
Our opportunistic Canadian equity sector guidance follows:
Overweight for energy, industrials, and materials
Neutral for technology, health care, real estate, and utilities
Underweight for communication services, consumer discretionary, consumer staples, and financial services and financial services
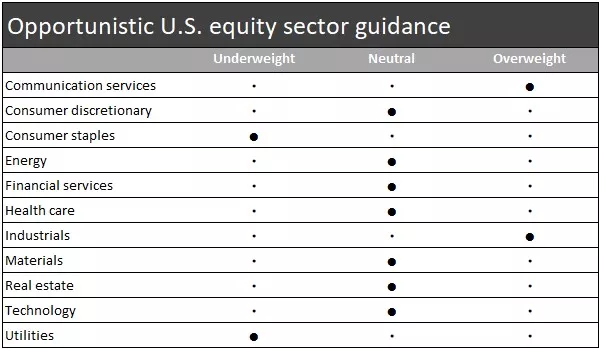
Our opportunistic U.S. equity sector guidance follows:
• Overweight for communications services and industrials
• Neutral for consumer discretionary, financial services, energy, real estate, technology, health care and materials
• Underweight for consumer staples and utilities
Our opportunistic U.S. equity sector guidance follows:
• Overweight for communications services and industrials
• Neutral for consumer discretionary, financial services, energy, real estate, technology, health care and materials
• Underweight for consumer staples and utilities
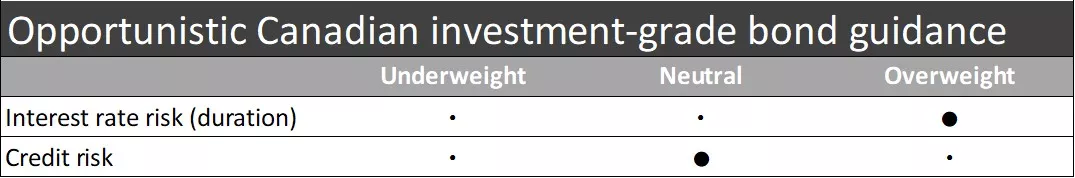
Our opportunistic Canadian investment-grade bond guidance is overweight in interest rate risk (duration) and neutral in credit risk.
Our opportunistic Canadian investment-grade bond guidance is overweight in interest rate risk (duration) and neutral in credit risk.
Tom Larm, CFA®, CFP®
Tom Larm is a Portfolio Strategist on the Investment Strategy team. He is responsible for developing advice and guidance related to portfolio construction, asset allocation and investment performance to help clients achieve their long-term financial goals.
Tom graduated magna cum laude from Missouri State University with a bachelor’s degree in finance. He earned his MBA from St. Louis University, is a CFA charter holder and holds the CFP professional designation. He is a member of the CFA Society of St. Louis.
Important information
Past performance of the markets is not a guarantee of future results.
Diversification does not ensure a profit or protect against loss in a declining market.
Investing in equities involves risk. The value of your shares will fluctuate, and you may lose principal. Mid- and small-cap stocks tend to be more volatile than large-company stocks. Special risks are involved in international and emerging-market investing, including those related to currency fluctuations and foreign political and economic events.
Rebalancing does not guarantee a profit or protect against loss and may result in a taxable event.
Before investing in bonds, you should understand the risks involved, including credit risk and market risk. Bond investments are also subject to interest rate risk such that when interest rates rise, the prices of bonds can decrease, and the investor can lose principal value if the investment is sold prior to maturity.
The opinions stated are as of the date of this report and for general information purposes only. This information is not directed to any specific investor or potential investor, and should not be interpreted as a specific recommendation or investment advice. Investors should make investment decisions based on their unique investment objectives and financial situation.