An October rotation: Three fundamental factors to watch
Key Takeaways
- Market leadership has rotated in recent weeks.U.S. technology has come under pressure in October amid concerns about AI-related debt, revenue expectations and higher rates, while investors have gravitated toward value stocks and more defensive sectors.
- We believe the fundamental backdrop remains supportive. Strong corporate earnings, resilient economic growth, and steady consumer spending continue to underpin the equity-market expansion, even as market volatility emerges.
- Stay focused on long-term goals. Diversification can help reduce exposure to single themes and smooth volatility. We continue to favour equities over fixed income, with a preference for U.S. large- and mid-cap stocks, while shorter-duration investment-grade bonds offer attractive yields relative to cash, in our view. Investors should evaluate these opportunities in the context of their financial goals, risk tolerance, and time horizon.
October surprise: Sector rotation away from U.S. AI and tech
October has thus far lived up to its spooky reputation for market uncertainty. Equity and bond markets are navigating several headwinds, including elevated inflation and energy prices, and government bond yields near their highs for the year. Even so, the S&P 500 remains up about 12% year to date, and the Canadian TSX is up about 14%, although both indexes have traded largely sideways since August.
Beneath the surface, sector performance points to a more cautious tone. In the U.S., for the full year, energy and technology still lead the pack, with both sectors up more than 20%. However, in October thus far, energy has maintained its lead but has been followed by defensive areas such as consumer staples, health care and utilities. Technology has been the worst performer for the month, falling into negative territory.
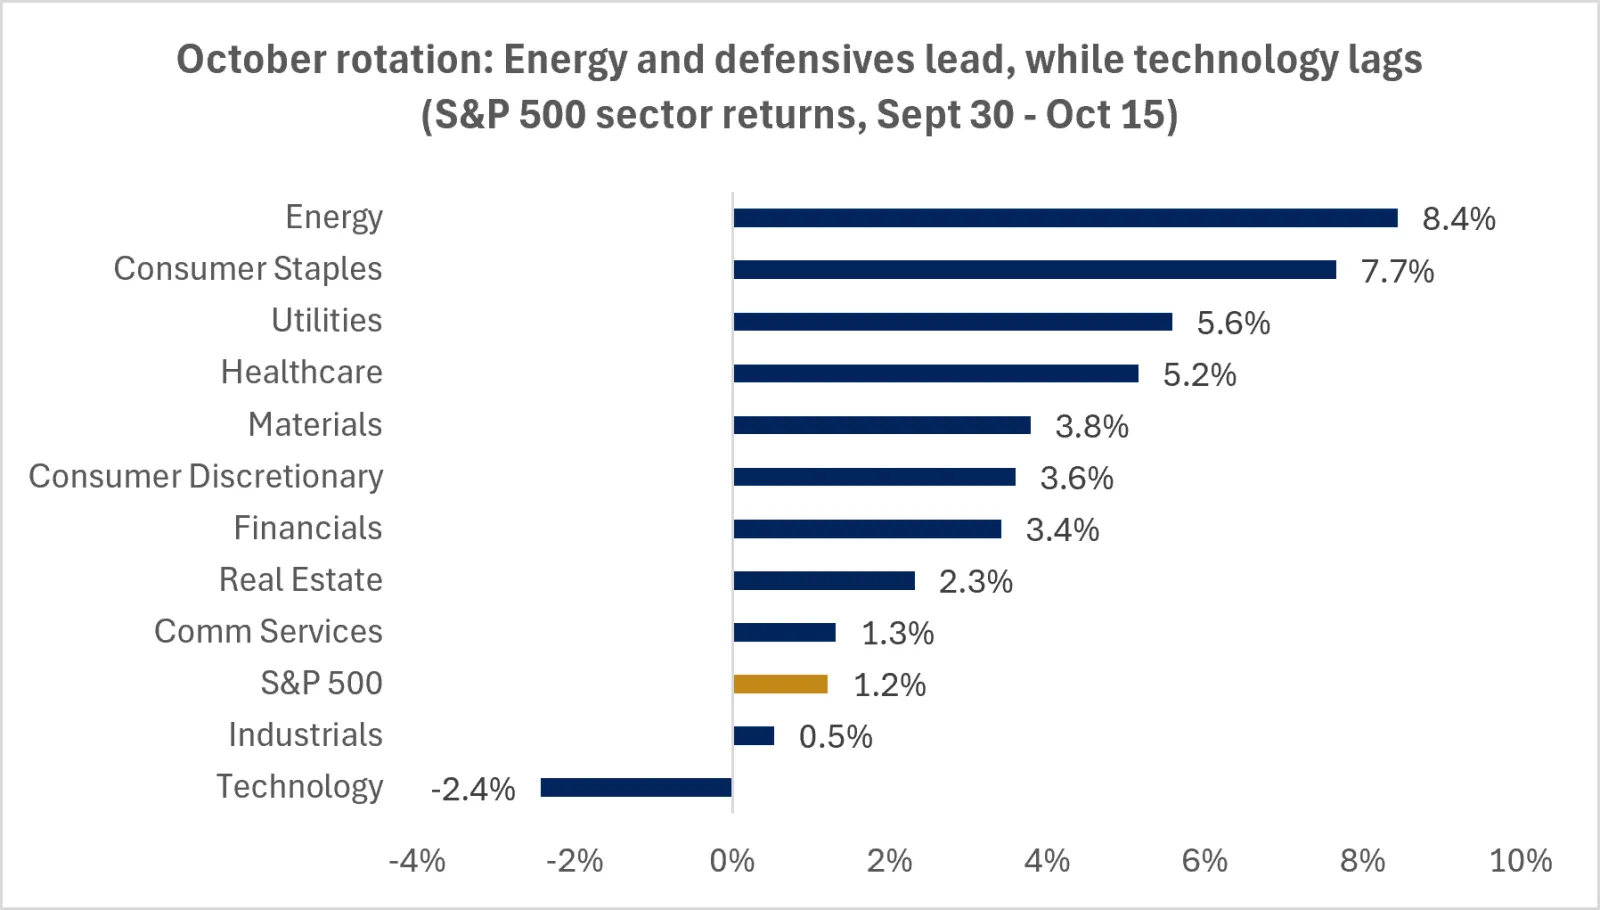
The chart shows that energy and defensives are leading performance in October, while technology lags. Past performance doesn't guarantee future results. Indexes are unmanaged, cannot be invested into directly and are not meant to depict an actual investment.
The chart shows that energy and defensives are leading performance in October, while technology lags. Past performance doesn't guarantee future results. Indexes are unmanaged, cannot be invested into directly and are not meant to depict an actual investment.
The move lower in technology has been driven by a few factors. First, we have seen outsized sell-offs in those AI companies taking on higher debt but have less free cash flow cushions, including names like CoreWeave and Oracle. There has also been growing concern that revenue growth may not be keeping up with lofty expectations, based partly on recent revenue reports from AI giants like Anthropic and OpenAI. This has weighed on areas like semiconductors as well. And finally, higher rates have weighed on the sector, especially as debt-financing becomes a larger source of capex funding.
Investors instead have gravitated toward more defensive parts of the market. We have seen better performance from value stocks, defensive sectors, and even bond markets moving higher as investors gravitate toward more safe-haven assets. This has also benefited the Canadian equity market, which has higher weights to sectors like financials, materials, and energy. The Canadian TSX is higher by almost 2.5% in October. This recent rotation suggests that investors may be seeking quality and defensive investments in the face of elevated headwinds. However, we continue to see fundamental factors that support the ongoing equity market expansion.
Three fundamental factors supporting the market
As we know, market volatility is the norm in any given year. In fact, on average, stock markets experience one to three pullbacks in the 5% to 15% range. This year, the S&P 500 has experienced just one 10% pullback in March, when the Iran war began. While we may see bouts of market volatility, we continue to see three fundamental pillars supporting the equity market outlook:
1. Corporate earnings growth remains strong. Corporate earnings growth for the S&P 500 companies is on pace to exceed 30% this year, while the Canadian TSX is expected to see about 29% earnings growth. These are the highest growth rates since 2021, when the global economy was emerging from the pandemic downturn.
We are currently in the early days of third-quarter earnings season, which is also expected to see earnings growth of about 29% in both the U.S. and Canada. For the S&P 500, technology, communication services, energy and materials are leading, but 10 of the 11 S&P 500 sectors are expected to report positive earnings growth this quarter. And in Canada, nine of the 11 sectors are forecast to have positive earnings growth. Strong corporate earnings underpin stocks and remain a key supportive factor in equity market appreciation over time.
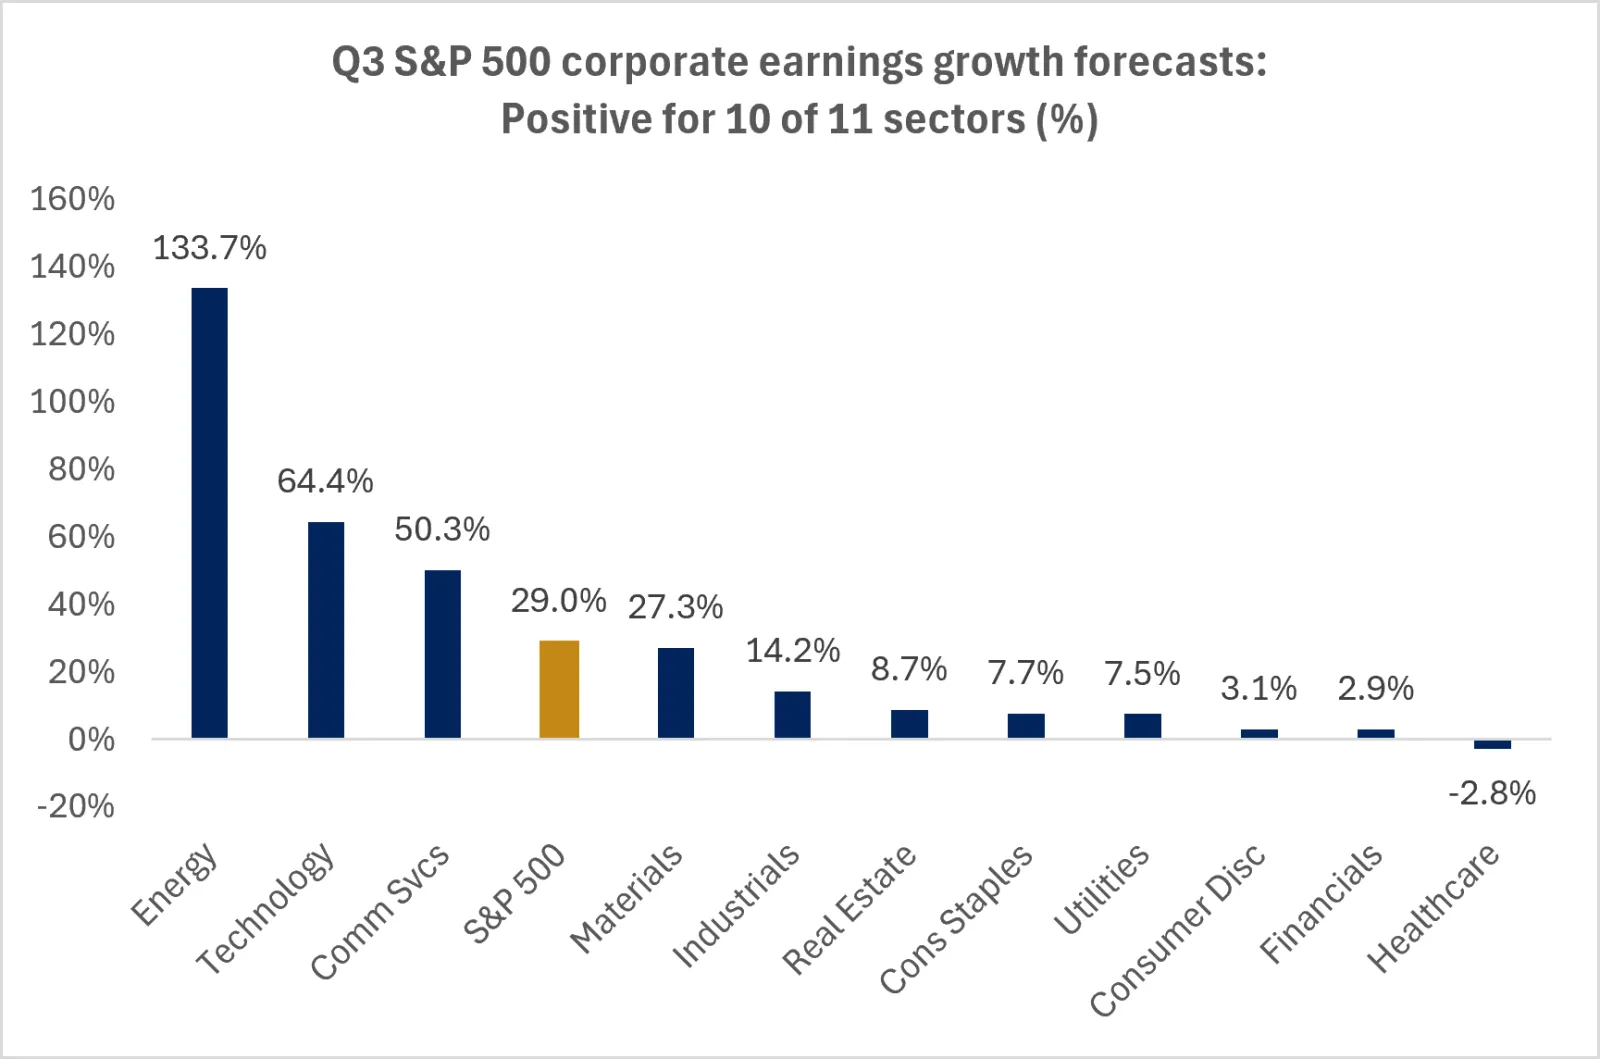
The chart shows that 10 of the 11 S&P 500 sectors are forecast to have positive earnings growth for Q3. Indexes are unmanaged, cannot be invested into directly and are not meant to depict an actual investment.
The chart shows that 10 of the 11 S&P 500 sectors are forecast to have positive earnings growth for Q3. Indexes are unmanaged, cannot be invested into directly and are not meant to depict an actual investment.
2. Economic growth continues to hold up. We also have seen U.S. economic growth remain resilient in the face of rising rates and elevated inflation. Both the manufacturing and services sectors of the economy have been growing, with PMI (purchasing manager index) levels above 50 this year, indicating expansion.
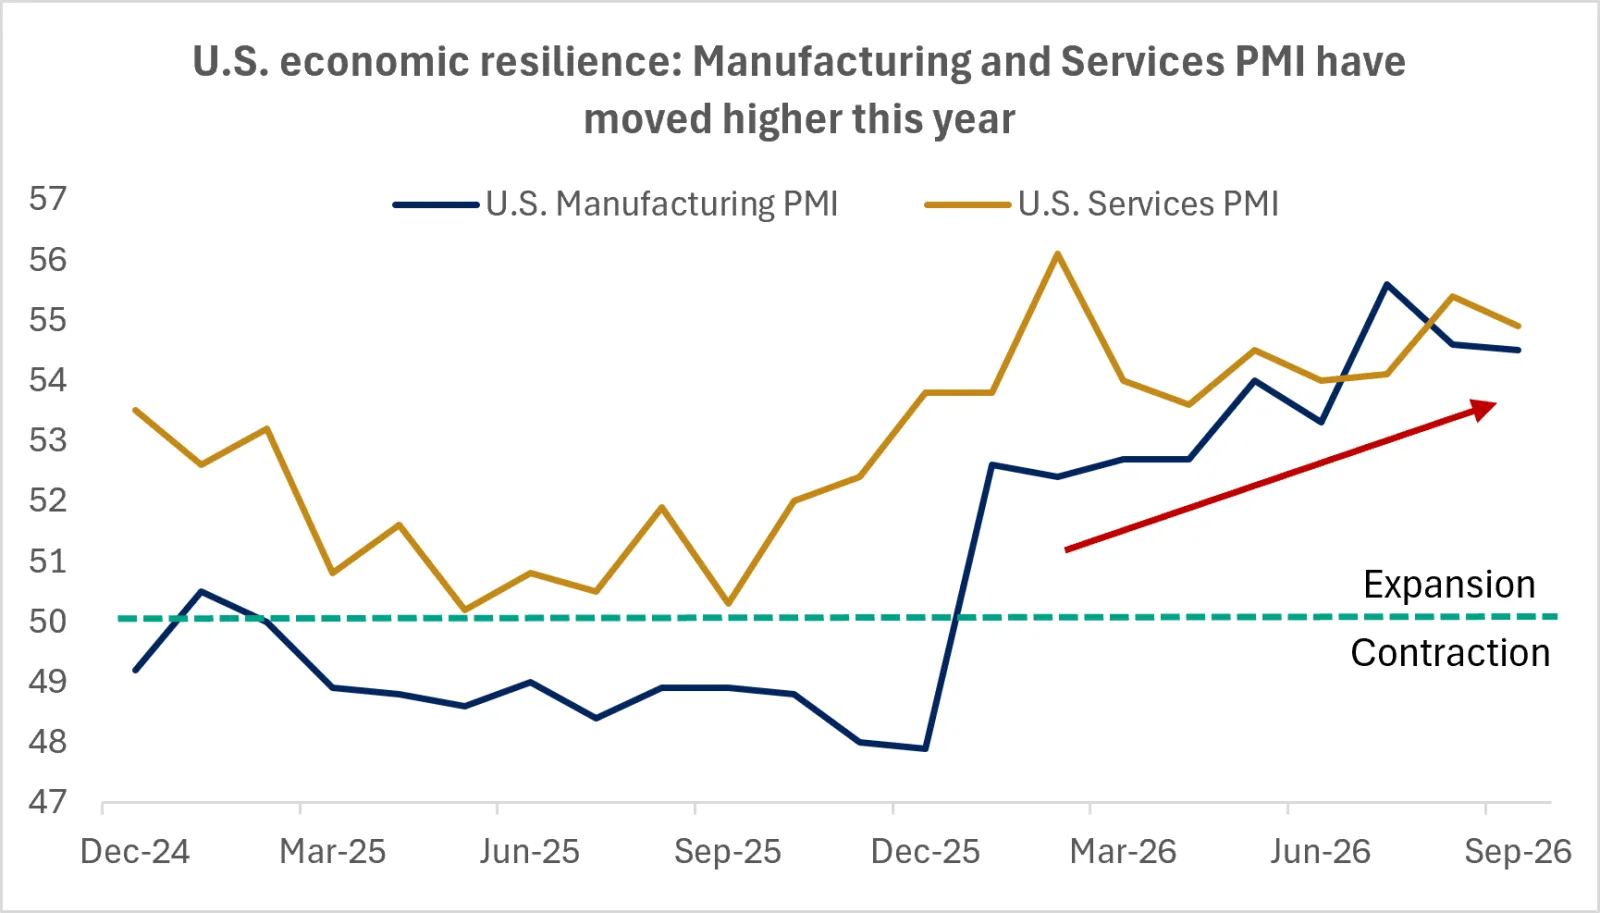
The chart shows that U.S. Manufacturing and Services PMI have moved higher this year.
The chart shows that U.S. Manufacturing and Services PMI have moved higher this year.
In Canada, the manufacturing sector has been in expansion for six straight months, although momentum has been fading more recently. In addition, the services sector remains in contraction, in part weighed down by tariff uncertainty and elevated energy and transportation costs. Nonetheless, GDP growth in Canada last month came in at a healthy 1.4%, above forecasts of 1.3%.
3. The consumer remains resilient. Finally, data indicates that household consumption has remained resilient. In the U.S., last week's September retail sales, for example, rose 0.8% for the month, ahead of the 0.3% forecast, suggesting that households continue to spend even in the face of elevated prices. In addition, big bank earnings reports last week also signaled that consumer spending and credit are still solid, supported by a steady labour market. In Canada, the labour market remains resilient, with the unemployment rate at 6.5% last month, although this is a tick higher than the prior 6.4% reading. We know that consumption makes up about 70% of U.S. GDP, and about 60% of Canadian GDP, and a resilient consumer is a good sign for the broader economy.
Bottom line: We do not see a recession or economic downturn in the near-term horizon, supported by strong earnings and solid economic growth and consumption. While volatility and periodic market resets are normal, we believe the fundamental backdrop continues to underpin the equity market expansion.
On the radar: What we are watching next
As we head toward the final months of the year, we are watching several key market events that could be meaningful catalysts in the weeks ahead.
October 19: Alberta referendum. Albertans head to the polls on October 19 to vote on several issues, including immigration, constitutional matters and whether Alberta should pursue greater autonomy from Canada, including support for a future referendum on independence. While the results are non-binding, they will provide an important indication of public sentiment and could influence future provincial and federal policy discussions in a province that plays a critical role in Canada's energy sector and broader economy. Supporters of greater autonomy argue that Alberta does not receive a proportionate share of the economic benefits generated by its natural resources and lacks sufficient influence over federal decision-making.
While the vote would not directly alter Alberta's status within Canada, strong support for greater autonomy or a future independence referendum could add to political uncertainty and increase pressure on policymakers to address issues related to energy development, resource infrastructure and federal-provincial relations. In our view, the prospect of a binding referendum on Alberta's separation remains low, and the likelihood of Alberta ultimately leaving Canada is lower still. Nevertheless, the outcome will be closely watched by policymakers and markets, as it may influence the federal government's approach to economic development, energy policy and nation-building initiatives.
October 28: Federal Reserve and Bank of Canada (BoC) interest rate decision. Second, we will also have both central bank interest rate decisions on Wednesday, October 28. We believe both the Fed and BoC may opt to remain on hold and take a more gradual path and perhaps consider a rate hike at the December meeting, if conditions warrant. Markets may also welcome the notion of a less aggressive rate-hiking cycle. In addition, we will be listening for the central banks' take on inflation, the labour market, and the path of policy rates going forward.
Nov. 3: Midterm elections. Finally, U.S. midterm elections will be held on November 3. While politics and elections alone tend not to sway stock market fundamentals, we know that historically a divided government has not been a headwind for markets. In fact, since 1970, the S&P 500 has rallied in the six months following midterms, regardless of the outcome. Read more insights in our Midterm Election piece here: https://www.edwardjones.ca/ca-en/market-news-insights/stock-market-news/market-pulse/midterms-markets-lessons-history-considerations-today
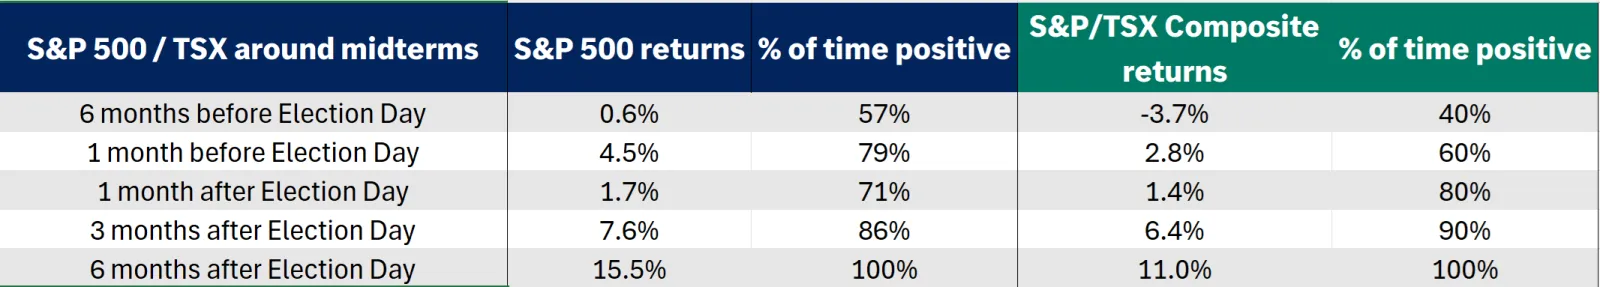
The table shows S&P 500 and TSX total returns around the U.S. midterm election day since 1970. Past performance doesn't guarantee future results. Indexes are unmanaged, cannot be invested into directly and are not meant to depict an actual investment.
The table shows S&P 500 and TSX total returns around the U.S. midterm election day since 1970. Past performance doesn't guarantee future results. Indexes are unmanaged, cannot be invested into directly and are not meant to depict an actual investment.
Portfolio positioning
Overall, the October rotation and volatility may feel unsettling for investors. However, we continue to see resilient fundamental factors of strong corporate earnings and solid economic growth and consumption supporting the ongoing equity expansion.
In this backdrop, we continue to favour equities over fixed income investments. Within equities, we prefer U.S. large-cap stocks and Canadian small and mid-cap stocks, which can provide exposure to both growth and defensive parts of the market. And within investment grade bonds, we see value in shorter duration bonds, which offer a favourable pick-up in yield versus cash, in our view.
Your financial advisor can help ensure that your investments are diversified and well-positioned in the context of your financial goals and risk tolerance, regardless of what October or the rest of this year brings.
Mona Mahajan
Investment Strategist
Source for all data in commentary: Bloomberg and FactSet
Previous weeks' weekly market wraps
10/9: Four Years In: What Makes This Bull Market Different?
10/2: Rising rates, resilient economy: What history suggests for markets
9/25: Navigating a Higher Interest Rate World
9/18: What the Fed's first hike in three years means for investors
9/11: Oil Raised the Question, CPI Delivered the Answer
9/4: Three Datapoints the Fed Is Likely Watching Ahead of the September FOMC Meeting
Important information:
The Weekly Market Update is published every Friday, after market close.
This is for informational purposes only and should not be interpreted as specific investment advice. Investors should make investment decisions based on their unique investment objectives and financial situation. While the information is believed to be accurate, it is not guaranteed and is subject to change without notice.
Investors should understand the risks involved of owning investments, including interest rate risk, credit risk and market risk. The value of investments fluctuates and investors can lose some or all of their principal.
Past performance does not guarantee future results.
Market indexes are unmanaged and cannot be invested into directly and are not meant to depict an actual investment.
Diversification does not guarantee a profit or protect against loss.
Systematic investing does not guarantee a profit or protect against loss. Investors should consider their willingness to keep investing when share prices are declining.
Dividends may be increased, decreased or eliminated at any time without notice.
Special risks are inherent to international investing, including those related to currency fluctuations and foreign political and economic events.
Before investing in bonds, you should understand the risks involved, including credit risk and market risk. Bond investments are also subject to interest rate risk such that when interest rates rise, the prices of bonds can decrease, and the investor can lose principal value if the investment is sold prior to maturity.